
Parallel Systems
Ex-SpaceX engineers building autonomous, battery-electric freight rail vehicles — a Series C underwriting a bet on short-haul modal shift from truck to rail
Parallel Systems is a Los Angeles-based rail technology and manufacturing company founded in 2020 by Matt Soule. The company states that Soule spent 13 years at SpaceX. Coverage at the company’s 2022 emergence from stealth described the founding group as former SpaceX engineers, with additional alumni of Google and Tesla on the team. We read this as an outsider-built model: a team that brings manufacturing, autonomy and systems-engineering discipline to an asset class with limited technological turnover, rather than a rail incumbent’s internal incubator.
Founded the company in 2020 after 13 years at SpaceX (company-stated). The principal spokesperson on the Series B and Series C announcements, emphasizing the transition from pilot to production and a team that pairs engineers with rail operations professionals.
Carries the external message on the Series C and the Agility agreement. His public profile (LinkedIn) lists Harvard University and prior founder, CEO and board-chair roles. In the Series C release he said the question has moved from “if” to “how soon” for railroad adoption.
Preqin lists Brian Ignaut, John Howard and Ben Stabler alongside Soule. Contemporaneous 2022 coverage described three former SpaceX engineers as founders, so the headcount differs by source.
G&W short lines Georgia Central Railway and Heart of Georgia Railroad are the operating partners in the FRA-supervised Georgia pilot. G&W has publicly pointed to the potential to revive rail traffic on rural lanes now dominated by truck.
(1) Co-founder identity and headcount differ across sources (three versus four) and we found no company-confirmed roster. (2) Mr. Gupta’s career detail rests on a public profile summary and has not been independently verified. (3) Mr. Soule’s SpaceX tenure and role are company-stated. We do not treat these items as established fact pending verification.
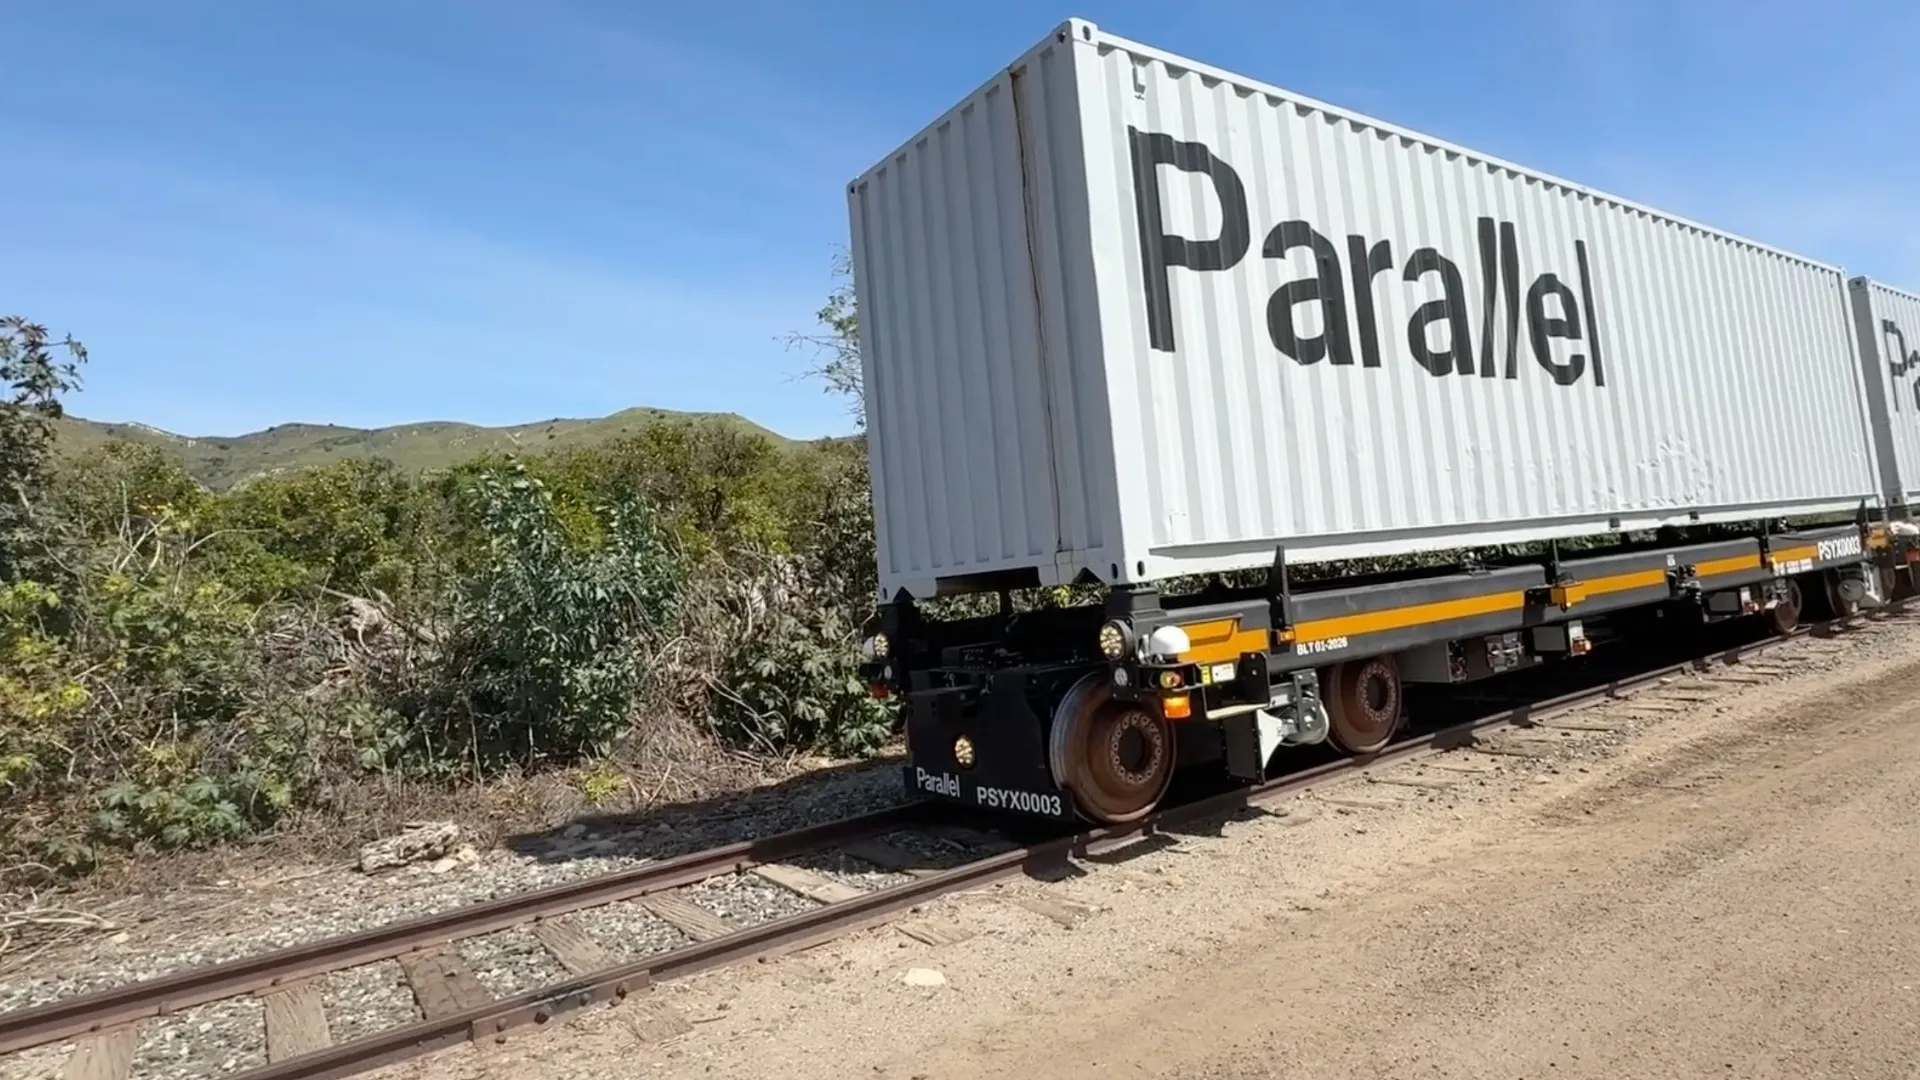
Parallel develops self-propelled, battery-electric rail vehicles that carry shipping containers individually or in small platoons. Per the company, each vehicle has its own braking, which removes the need for a locomotive and air-brake line connections, and platoons of 10 to 30 vehicles can form without physical couplers. The intent is to rebuild rail unit economics on short, low-density routes where unit-train economics do not apply. We characterize the business model as a systems vendor selling integrated hardware and software that lets a railroad (the customer) address short-haul freight it cannot serve profitably today.
| Timing | Milestone | Status | Notes |
|---|---|---|---|
| 2020 | Company founded; seed funding | Done | Seed of $3.6M |
| Jan 2022 | Exit from stealth; Series A; Mark 1 and Mark 2 prototype testing | Done | Mark 1 tested on a closed track near Los Angeles; Mark 2 followed |
| Aug 2023 | G&W subsidiaries petition FRA to approve a pilot | Done | Railroad-led regulatory filing is notable |
| Feb–Apr 2025 | FRA approves a seven-phase test program (notice Feb 2025); testing begins | Done | Approval and start dates vary by report (see flag) |
| Jun–Sep 2025 | Georgia pilot moves from Phase 1 to Phase 2 with expanded capability and range | In progress | RailFreight reported first commercial tests completed in Sep 2025 |
| Sep 28, 2026 | Strategic collaboration with Agility’s corporate venture arm for GCC and EMEA | Early | Initial step is identifying priority corridors; scope spans development, commercialization, financing and deployment |
| Oct 7, 2026 | Series C of $100M closes; Panther production scale-up | In progress | Company says multiple major railroads are under contract (customers undisclosed) |
| TBD | Australian railroad commercialization | Exploratory | Cited as a use of Series B proceeds; current status unverified |
Our view — the inflection is pilot-to-production: The company says it has moved since its 2025 Series B from prototyping to live operation under a regulatory test approval. We read the Series C as capital for Panther volume production and order fulfillment, premised on the Georgia pilot’s technical validation. Because FRA testing proceeds in approved phases, we would treat the pace of pilot-phase progression as the gating variable for both production timing and international expansion.
(1) Revenue, contract values, pricing and per-vehicle unit economics are not disclosed. (2) The 300+ vehicle backlog is an April 2025 company figure and was not restated in the Series C release, which refers only to multiple major railroads under contract; the only named counterparty is G&W. (3) Range of up to 500 miles, energy use of roughly 25% of a semi-truck (a 2022 company estimate) and “up to 10 times faster stopping than a train” are company claims with no third-party verification that we could locate. (4) FRA approval timing appears as a February 2025 notice in one source and an April 2025 test start in others; we do not assign a single date. (5) We could not confirm progress on the Australian initiative after 2025 reporting.
Parallel is privately held, and the company says cumulative funding exceeds $200 million. Disclosed rounds sum to roughly $191 million: seed of $3.6M, Series A of $49.55M, Series B of $38M and Series C of $100M. Three features stand out to us. First, Anthos Capital led the Series A and Series B and participated again as an existing investor in the Series C, which signals sustained conviction from the earliest institutional backer. Second, the Series C lead passed to a new investor, AVP, broadening the cap table. Third, the strategic character of Agility Global’s participation ties this financing directly to the Gulf and EMEA commercial agenda.
Initial capital raised shortly after founding. We found limited public detail on individual participants; the round was disclosed when the company emerged from stealth with its Series A.
Led by Anthos Capital. Proceeds funded prototype testing, hiring and an extended test program; cumulative funding was reported at $53.15M at the time. Shortly after the announcement, some industry experts questioned whether the concept adequately accounted for the regulatory, operational and labor realities of the existing U.S. rail network.
Led by Anthos Capital. Proceeds were earmarked for commercialization with U.S. and Australian railroads and the start of the Georgia pilot. Cumulative funding was guided to “about $100 million” at announcement.
Led by new investor AVP. Capital is directed to expanding production of the third-generation Panther vehicle, full commercialization and entry into international markets. The round is roughly 2.6x the Series B. The release headline reads “$100M+” while the body states “$100 million in new capital,” so we cannot confirm whether any amount exceeds $100M.
Our view — what the syndicate signals: Participation by all four named existing investors (Anthos, Congruent, Riot and Collaborative Fund) reads to us as an insider vote of confidence in pilot progress. That said, we think the more consequential feature of this round is Agility Global’s entry rather than its size. Agility is the counterparty on the GCC and EMEA development, financing and deployment agreement, so the financing couples capital with an international go-to-market channel.
(1) Cumulative total does not reconcile. Disclosed rounds sum to about $191M ($3.6M + $49.55M + $38M + $100M), while the company cites “about $100 million” raised as of April 2025 and “more than $200 million” now. Seed plus Series A of $53.15M plus Series B of $38M gives about $91M, leaving roughly $9M unexplained by public sources (an undisclosed extension or rounding are possibilities). (2) No valuation has been disclosed for any round. (3) Investor naming varies. Riot appears as both Riot Ventures and Riot Capital; Embark Ventures is confirmed in the Series A but is absent from the Series C existing-investor list; Milano Investment Partners and 8090 Industries appear only in Preqin data and we could not cross-check them against company releases. (4) Use of proceeds is not quantified; the split of Series C between production, international expansion and R&D is not disclosed.
Parallel competes on three fronts: battery-electric locomotives (such as Wabtec’s FLXdrive), small autonomous rail vehicle developers (such as Intramotev), and the incumbent short-haul mode itself, trucking, including autonomous trucking. We believe Parallel’s differentiation lies not in any single technology but in the combination of product architecture, regulatory head start, railroad channel and international expansion optionality.
Each vehicle carries its own propulsion, braking and autonomy, removing dependence on locomotives and long consists. Small platoons target routes under 500 miles and low-density lines where unit-train economics fail; the company puts this at roughly 60% of the surface freight market.
A seven-phase FRA-approved test program is under way on a 160-mile segment. Because G&W led the regulatory petition, regulatory and operating risk is shared with the customer. We see a barrier-to-entry effect in accumulating regulatory data and operating history first.
Vehicles self-sort, assemble into platoons and integrate with existing rail control and business systems, using camera-based perception and redundant braking. Interfacing with legacy signaling and dispatch is, in our view, a meaningful hurdle for fast followers.
The company says multiple major railroads are under contract (customers undisclosed) and disclosed a 300+ vehicle backlog in April 2025. Selling to railroads, who are also the regulatory partner, should meet less commercial resistance than entering the trucking market directly.
LFP battery-electric propulsion with, per a 2022 company estimate, energy use of about a quarter of a semi-truck’s. The value proposition aligns with decarbonization and road-congestion priorities, particularly on port-linked corridors.
The Agility agreement targets port shuttles, links to inland logistics sites and city-to-city freight, starting with corridor identification. The argument is that emerging rail networks can design autonomous battery-electric technology in from the outset. Australia has also been cited as an early target market.
| Competitor Type | Representative | Approach | Our Assessment |
|---|---|---|---|
| Small autonomous rail vehicles | Intramotev (TugVolt) | Battery-electric autonomous rail cars aimed at industrial switching and short-haul; reported commercial agreement with R.J. Corman | The most direct comparable, though weighted toward mining and yard use. We view Parallel as ahead in intermodal platoon operation |
| Battery-electric locomotives | Wabtec FLXdrive; Progress Rail EMD Joule | Locomotive electrification to cut diesel use in heavy-haul and yard service | A locomotive-centric architecture addresses a different problem than low-volume short-haul. Incumbents hold advantages in railroad purchasing relationships and installed base |
| Trucking and autonomous trucking | Short-haul freight generally | Door-to-door flexibility; autonomy would improve driver-cost structure | The real incumbent and the target of modal shift. Mr. Soule has himself said Parallel must stay ahead of autonomous trucking |
Our overall assessment: Parallel is positioned less as a rail electrification vendor than as a systems supplier that gives railroads a way into short-haul freight. In that structure, railroad purchasing intent and phased FRA approvals govern the pace of revenue recognition, in our view. We would therefore watch three checkpoints: pilot phase progression, the conversion of the major-railroad contracts into named, quantified orders, and the start of Panther volume production.
(1) Product performance, market size and order figures in this section rest largely on company releases and have not been audited or independently verified. (2) The $1 trillion market size and the 60% short-haul share are figures cited by the company; the underlying methodology is not disclosed. (3) Competitor product and contract status (Intramotev, Wabtec and others) draws on secondary reporting that we did not verify directly. (4) The Series C release uses promotional language, including “the world’s leading” autonomous freight rail company, which we have not adopted as statements of fact.